
AuraDot
From disposal to asset. From consumers to producers.
AuraDot turns textile waste into green methanol and energy sovereignty.
NEEDS
01 — Waste as Export Liability
120+ million tonnes of textile waste are generated globally each year. Currently, 80% of this waste ends up in one of three problematic pathways: landfill (where it occupies space and leaches chemicals for decades), incineration (where energy is wasted and emissions released), or export to regions with weaker environmental regulations and less political power to enforce standards.
This export model reflects a form of generational inequality that has persisted for decades. Wealthy nations create the waste—through fast fashion consumption, industrial textile production, and discarded consumer goods—and then outsource the responsibility to communities elsewhere. The waste becomes someone else's environmental burden.
But this paradigm is shifting globally. Regulatory pressure (Extended Producer Responsibility directives, circular economy mandates) and growing recognition of injustice are forcing nations to confront a fundamental question: what if we owned this problem rather than exporting it?
The critical insight is that waste is not inherently a disposal problem. Waste is energy and material value that has been locked away in forms we haven't yet transformed. Textile waste contains carbon, hydrogen, and other elements that can be converted into useful products. The problem isn't the waste itself—it's our historical lack of viable technologies and business models to valorize it.
AuraDot addresses this globally by providing a pathway to transform waste from a liability into an asset, enabling communities everywhere to own their waste problems and build local prosperity from them.
02 — The Energy Vulnerability
Simultaneously, the world faces a structural energy vulnerability that makes the timing particularly urgent. Driven by maritime decarbonization mandates (IMO Net-Zero Framework), renewable energy targets, and net-zero commitments from major chemical, energy, and shipping companies, global demand for green methanol is projected to reach 7 million tonnes per year by 2030.
However, current global green methanol production capacity stands at only 6.5 Mt/yr, and most of this is already contracted to offtakers. This creates a supply gap of approximately 0.5–1.5 Mt/yr that persists through 2030 even accounting for announced capacity expansions. This shortage is not incidental; it reflects structural constraints in how green methanol is currently produced.
The dominant pathway is via centralized mega-plants that rely on green hydrogen infrastructure, which itself is immature and expensive. These mega-plants require 5–7 years of development and €750M+ in capital investment. They compete for limited hydrogen infrastructure, green power access, and financing—all of which are constrained globally. Worse, they create geographic concentration risk: a handful of mega-plants becoming bottlenecks for supply across entire regions. Geopolitical disruptions (port congestion, political instability, supply chain breaks) can disrupt access for months.
This is precisely the kind of structural vulnerability that policy-makers and energy security specialists worry about globally. Recent energy crises and supply shocks have demonstrated that centralized supply creates fragility.Distributed, local production is the antidote.
03 — Segmented Silos Seeking Co - Creation
Beneath the headline numbers, there are three distinct stakeholder groups, each operating in relative isolation with their own constraints and incentives, each facing mounting pressure to change:
Waste Operators (textile sorting hubs, sawmills, forest operators) face mounting disposal costs for unsortable mixed-fiber textiles and residual wood. Recycling infrastructure has reached its limits—it abandons anything contaminated or complex. These waste streams have no profitable circular outlet. Disposal costs €50–100/t, and these costs are rising as landfill capacity tightens and incineration regulations strengthen.
Energy & Industrial Offtakers (district heating operators, chemical manufacturers, shipping companies, maritime operators) need green methanol but lack supply certainty. Utilities pursue renewable energy mandates with no local supply chain. Chemical manufacturers need methanol as feedstock and thermal energy to meet sustainability reporting requirements. Shipping operators face mandatory decarbonization standards. All are caught between regulatory pressure and scarcity—unable to secure reliable, circular methanol supply.
Communities face energy insecurity and dependence on centralized grids. They lack economic agency—energy is produced elsewhere and distributed to them. They lack resilience—supply disruptions cascade without local alternatives. They lack prosperity—economic value flows away.
Urgent global policy mandates create genuine time pressure. Fear of being left behind as competitors lock in supply drives stakeholders to seek partnerships now. But they're seeking something specific: co-shared value creation. They want co-owned revenue streams that enable local resilience, energy sovereignty, and regional economic independence—not continued dependence on centralized supply chains.
This is where segmented silos meet urgent common need.
04 — Market Size & Urgency Window
Feedstock availability:120 million tonnes of textile waste annually (growing at 3 - 5% per year as consumption increases). 400 - 600 million tonnes of forest and wood residues annually (largely underutilized; competing with bioenergy subsidies and pulp industry). Combined: sufficient to support 8 - 12 Mt/yr of methanol production if fully utilized
Supply gap: Current green methanol production: 6.5 Mt/yr (mostly contracted). Projected demand by 2030: 7 Mt/yr (shipping) + 2 - 3 Mt/yr (chemicals, heating, other) = 9 - 10 Mt/yr. Unmet demand: 0.5 - 1.5 Mt/yr through 2030 (shortage period is real and measured)
Policy deadlines creating urgency: CBAM (Carbon Border Adjustment Mechanism) effective Jan 1, 2026: Buyers begin paying embedded carbon costs on grey methanol imports; green methanol becomes cost - competitive. FuelEU Maritime penalties start 2025: Shipping operators face financial penalties for non - compliant fuels; they must secure green supply now. RED III compliance dates: EU and member states have binding renewable energy targets with legal consequences for missing targets. IMO Net - Zero Framework enters force Feb 2028: Shipping industry must comply with mandatory GHG reduction standards starting first reporting year 2028
Urgency window: 2025 - 2028: This is not a distant, hypothetical market. These are laws. These are enforcement mechanisms. Buyers are motivated not by hope but by legal obligation. Willingness - to - pay is high because the alternative is penalties, stranded assets, or non - compliance fines. This is the most favorable demand environment AuraDot will see in the next decade.
APPROACH
01 — Technology: Co-Pyrolysis
AuraDot's core technology is co-pyrolysis—a thermal conversion process currently in proof-of-concept development. It transforms unsortable textile waste and wood residues (materials with no circular end-market) into two products:
Green methanol (targeting 8.0 gCO₂eq/MJ, 86% GHG reduction vs. grey). Designed to be RED III-compliant, CBAM-exempt, and FuelEU-compatible. Carbon intensity is low because feedstock (waste) would otherwise be landfilled or incinerated.
Biochar (stable carbon storage for 30–50 years). Secondary revenue stream via carbon credits or agronomic applications.
02 — Deployment: Smaller-Scale, Distributed Unit
Rather than betting on mega-plants, AuraDot deliberately deploys smaller-scale units at waste sources:
Timeline: 12–18 months vs. 5–7 years for mega-plants. Critical in the 2025–2028 urgency window.
Capital efficiency: Significantly lower capex per unit vs. mega-plants. Enables phased, de-risked investment across regions instead of betting entire capital on a single location.
Supply security: On-site production near waste sources = minimal logistics, maximum redundancy. If one unit has maintenance, others continue supply.
Modular & off-grid design: Units are engineered to include modularity and rapidly deployable across locations. The system is also designed to operate off-grid where renewable energy exists on-site, enhancing energy independence for hosting communities.
03 — Economics: Waste becomes Assets
Waste generators face disposal challenges globally: in some regions, disposal costs €50–100/t; in others, waste is abundant and underutilized. Regardless of regional context, waste currently has no profitable end-market or generates no revenue.
AuraDot creates economic value from waste. Waste generators become feedstock suppliers with revenue participation: In regions with disposal costs, gate fees flip costs to revenue. In regions where waste is abundant, AuraDot creates revenue where none existed. Across all contexts, waste transitions from liability to asset.
04 — Ecosystem Design: Co-Creation, Not Extraction
AuraDot isn't a traditional supplier selling fuel to distant buyers. It's a platform where all stakeholders co-own assets and share upside—a model that works across different economic contexts and regions:
Waste operators → revenue co-owners (feedstock partnerships with revenue participation)
Offtakers → equity co-owners (co-invest capex, earn supply certainty + equity returns)
Communities → energy participants and stakeholders (local jobs, revenue-sharing, energy autonomy)
Financiers → co-creators (direct investment, blended finance, carbon credit monetization)
Why it matters globally: Each stakeholder owns part of the asset and shares future revenue. This creates durable, aligned incentives that transcend traditional supplier-buyer relationships and work across diverse economic systems—from developed economies to emerging markets. The model isn't extraction (profit flows out); it's shared prosperity (value stays local, stakeholders benefit together).
BENEFITS
01 — Disposal Liability → Revenue Asset
Waste generators face different challenges globally: in some regions, disposal costs money; in others, waste is abundant but generates no revenue. Regardless, textile waste and wood residues currently represent a cost center or lost opportunity.
AuraDot transforms this: Waste becomes a valued feedstock with revenue participation. Waste generators shift from paying for disposal (or receiving zero value) to earning revenue from supply.
Waste generators become strategic suppliers, not waste managers. Their expertise in aggregating and processing waste becomes a competitive advantage. Revenue stays local, enabling job creation, skill development, and reinvestment.
Identity shift: From "managing our disposal problem" to "supplying feedstock to a circular energy system.”
02 — For Energy & Industrial Offtakers
Supply Certainty + Compliance + Green Financing + Energy Sovereignty
Supply certainty: Distributed production eliminates single-point-of-failure risk. Local supply hedges against geopolitical disruption and supply chain volatility. Long-term fixed-price contracts (3–5 years) provide budget certainty in volatile commodity markets.
Regulatory compliance: Green methanol satisfies global decarbonization mandates (renewable energy targets, carbon pricing schemes, maritime standards, corporate sustainability reporting requirements). Positions buyers ahead of tightening regulations and demonstrates circular sourcing to investors and stakeholders.
Green financing access: Certified circular fuel supply unlocks access to green financing instruments (green bonds, blended finance, impact investment). Lower cost of capital for organizations with visible sustainable supply chains.
Energy sovereignty: Co-ownership means you're not reliant on distant suppliers; you're a stakeholder in production. Local production reduces grid dependence and geopolitical vulnerability. Communities and buyers build energy autonomy together.
03 — For Communities
Energy Producers, Not Just Consumers
Communities transition from purchasing energy to hosting production. Local waste becomes local fuel. Production value stays local rather than extracted by distant corporations.
Energy independence: Distributed production enables local energy autonomy. Off-grid operation possible where renewable energy exists on-site. Insulation from global energy price shocks and supply chain volatility.
Economic revitalization: Local facility creates jobs (operations, maintenance, supply chain, administration). Economic multiplier effects as workers spend locally and supply contracts support regional businesses. For communities seeking economic opportunity and resilience, this represents genuine local development.
Participatory ownership: Revenue-sharing and investment opportunities enable communities to participate in upside. Economic benefits flow to local stakeholders, not distant investors. Communities transition from affected by energy decisions to shapers of local energy futures.
04 — Systemic: Nations Own Their Waste
Instead of exporting waste responsibility to regions with weaker regulations, nations transform waste into shared-capital opportunity. Waste becomes asset, not liability. Generational inequality becomes shared prosperity.
First-movers pioneer a new paradigm: Waste-as-shared-capital, circular value-chains, new institutional benchmarks for how energy is produced and waste is treated. The model works across different economic and regulatory contexts globally.
Long-term defensibility: Solution is aligned with global policy direction (2025–2030 onwards):
Renewable energy mandates: Waste-valorized fuels automatically qualify as renewable in most regulatory frameworks (no debate, structurally sound)
Carbon pricing: Green methanol gains permanent cost advantage over fossil fuels as carbon pricing expands globally
Maritime decarbonization: IMO Net-Zero Framework and regional shipping standards drive mandatory buyer demand
Sustainable finance: Circular waste solutions unlock access to green financing globally as ESG investment expands
This is structural alignment with global policy trends, not speculative betting on future policy.
COMPETITION
01 — Feedstock & Cost
Waste-based production costs significantly less than competing pathways (e-methanol, bio-methanol). Textile waste grows 3–5% annually; wood residues are vastly underutilized globally. No competition for feedstock across regions. This is structural, not temporary.
02 — Speed to Market
12–18 month deployment vs. competitors' 5–7 year timelines. AuraDot can deliver supply when global policy mandates take effect. Competitors' longer development cycles mean they miss the urgent compliance window. Distributed model deploys multiple units in parallel.
03 — Policy Alignment
Waste-valorized methanol aligns with global regulatory trends:
Renewable energy mandates: Waste automatically qualifies (no debate)
Carbon pricing: Green methanol gains permanent advantage vs. fossil fuels
Maritime standards: IMO Net-Zero Framework creates mandatory buyer demand
Sustainability reporting: Waste-based methanol = direct circular sourcing evidence
04 — Ecosystem Defensibility
Competitors (e-methanol, bio-methanol) compete on cost and availability. AuraDot creates ecosystem relationships (shared ownership, revenue participation) that transcend pricing. Once waste operators or offtakers commit, switching costs are high. Ecosystem defensibility outlasts technology differentiation.
05 — Market Timing
Global regulatory expansion (2025–2030 onwards) creates mandatory buyer demand. Buyers face legal compliance pressure, not optional upgrades. Willingness-to-pay is regulatory. Supply premium justified by certainty (distributed redundancy vs. centralized mega-plant risk).
06 — What AuraDot Is Not
Not cheaper than grey methanol (but grey is non-compliant with global decarbonization mandates; comparing AuraDot to compliant alternatives shows significant advantage)
Not a global-scale solution alone (addressable market focuses on specific, urgent segments; sufficient to address supply gaps and establish significant business at scale)
Not a long-term replacement for e-methanol or bio-methanol (both will eventually scale as hydrogen infrastructure matures and biomass costs improve; AuraDot's competitive window is 2025–2035, after which landscape shifts)
The Team
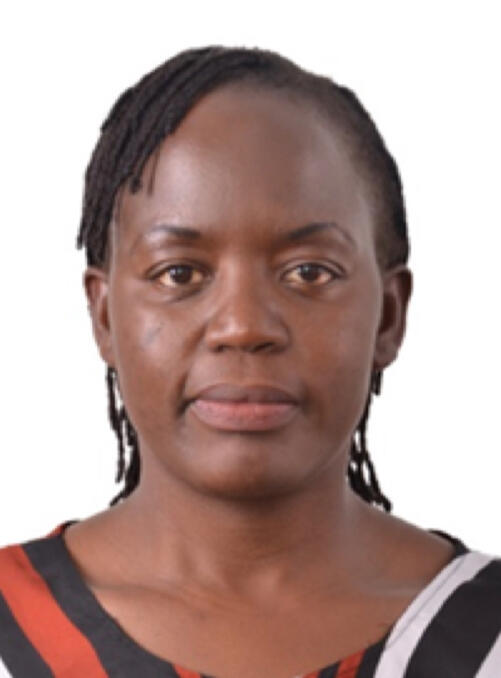
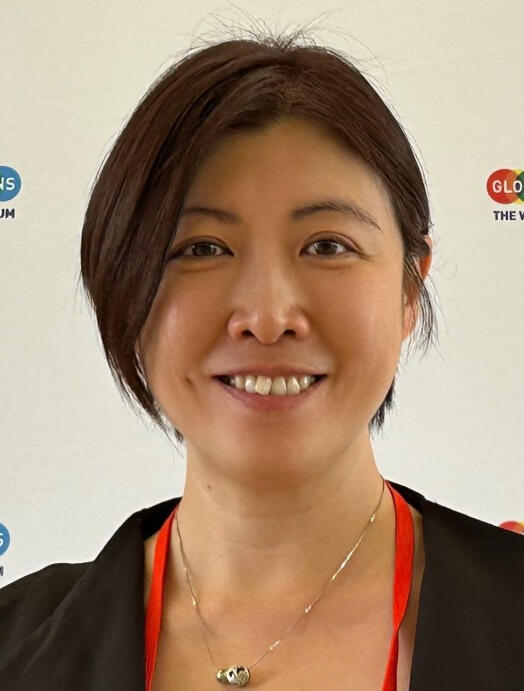
Founder | Technology
Lucy Ombaka
Founder | Commercial
Liwah Wong
⚈ Power-to-X
⚈ Net-Zero Chemistry
⚈ Nanotechnology
⚈ Advance Catalysis
⚈ Circular Economy
⚈ Climate to Capital
⚈ Regional Orchestration
⚈ Socio-Techno-Economic Modeling